The decision that never gets made
The traditional financial industry measures returns, assets and fees. Some of the most expensive outcomes in a client’s financial life don’t show up in any of them.
In its Mind the Gap study, Morningstar compares the returns funds produce with the returns investors actually receive. Over the ten years to the end of 2025, the average dollar invested in US mutual funds and ETFs earned 8.7% a year, against 9.9% for the funds’ aggregate annual total return. That gap of around 1.2 percentage points a year is
about 12% of the total return.
The difference comes from investor behaviour – the decisions people make about when to invest, when to withdraw and how much to commit. These decisions, often influenced by emotions, market conditions and behavioural biases, can mean investors capture less of the return their investments actually deliver.
None of that appears in the way performance is usually reported. The fund did its job. The portfolio was well built. The money still underperformed itself. And Morningstar is measuring only the return given up through the timing and size of
investors’ purchases and sales. It doesn’t try to measure what may be the higher costs, which often come from decisions not yet made. Those decisions don’t often appear in a performance report, but they may shape a financial life more than the returns on the page.
The costs nobody reports
Most of the expensive outcomes I see come from decisions that sit waiting. In a typical review, they look something like this:
- Proceeds from a business sale, bonus, inheritance or property sale still sitting in
cash. - A pension untouched since a change of country, employer or tax residence.
- A family has moved from the UK to the UAE, but their pensions, investments and
estate planning still reflect the life they left behind. - Life cover that ended with a previous employer and was never replaced.
- An investment strategy that exists on paper but is set aside when markets get
uncomfortable. - A portfolio has fallen, markets feel uncomfortable and a sensible long-term
investment strategy suddenly becomes “let’s wait and see”.
Why decisions stall
Samuelson and Zeckhauser named this status quo bias in 1988: people stick with what they already have, even when better options are available. It shows up in the decisions I see waiting at client meetings. Affluent investors are far from immune. HSBC’s 2024 survey of more than 11,000 affluent investors found that those in the UK held an average of 37% of their portfolios in cash, and 61% of all respondents had no plans to change their allocation. Cash has its place, offering security and flexibility. But it raises a fair question: how often do we keep an arrangement because it’s still right, and how often because changing it would mean making a decision?
Internationally mobile clients are especially exposed. Every move leaves a trail of half finished admin, and every change in residence can move away from what the old arrangements are trying to achieve. A plan that sits untouched while the rules and the client’s life move around it, is a plan that’s drifting. And drift always heads in a downward direction.
We manage what we measure
The traditional industry measures assets under management, returns against a benchmark, and fees. Those are the numbers in reports, pitch books and league tables, so that’s where most of our attention goes. The research points elsewhere. Vanguard’s Adviser’s Alpha research estimates that advisers following its framework may add around 3% in net returns over time, with behavioural coaching the largest single component. Vanguard is clear that this value
doesn’t arrive evenly. It tends to come in bursts, often when markets are falling or euphoric, and clients are most tempted to abandon the plan. That leaves our profession with an awkward problem. The year a financial life manager
talks a client out of a damaging move, or finally gets a stalled decision made, can look on paper like a quiet year. Some of the most valuable work we do involves sticking with the plan and promoting ‘no action’ and so goes unreported.
When is a decision overdue?
“Make decisions on time” is easy to say and hard to apply, so it helps to have a test. A decision is overdue when the cost of waiting is likely to be greater than the benefit of more information. Usually that’s because something has already changed: tax residence, family circumstances, liquidity or market exposure or because the decision has become dependent on predicting something that cannot reliably be predicted, such as the bottom of a market, the timing of a recovery or what markets will do next. If one of those has moved and the plan hasn’t, waiting has stopped being prudent.
Starting with what’s still waiting
At my reviews, I ask one question before we look at any numbers: what’s been decided since we last met, and what’s still waiting? A decision that keeps sliding from one meeting to the next is often not about missing information. Usually, the client is unsure what the money is for, or uneasy about the trade-offs. Helping them through that, so they can act with confidence, is a large part of what they’re paying for.
The real measure
At AES we practice Financial Life Management, which follows a fixed order: purpose, then plan, then portfolio. A plan is a series of decisions, made at the right time and for the right reasons. The portfolio follows from them. Assets matter, and so do returns. But they’re the result of something that happens earlier, in the moments when a client chooses to act or to wait. Helping people make smarter decisions at those moments, with clarity about what their money is for, is the heart of a financial life manager’s role. Most clients will never remember a quarter’s performance. They’ll remember the year they finally sold the business with a plan in place or put the right protection around their family before they needed it. A financial life is shaped less by what we own than by the decisions we make about it, and when.
About the author
Georgina Osborne-Stuart APFS is a Director of Financial Life Management at AES International in Dubai. AES is the only certified investment fiduciary in AMEA, advising internationally mobile professionals and families across the GCC.
She has spent 13 years in financial planning, advising senior partners at some of the world’s most respected law and accountancy firms. She combines deep technical expertise with a deeply personal approach, recognising that no two situations are alike and that great advice begins with truly listening.
For more information contact Georgina Osborne-Stuart, AES International – a Citywealth member.
Key Takeaways
- The article discusses how the decision that never gets made impacts financial outcomes, revealing a gap between expected returns and what investors actually receive.
- Behavioural biases lead investors to delay key decisions, which costs them potential gains.
- Common stalled decisions include leaving cash uninvested, not updating pension plans, and failing to replace lapsed life cover.
- This inertia, often due to status quo bias, affects affluent investors, causing them to hold excessive cash without plans to change allocations.
- Timely decision-making is crucial; clients must act with clarity about their financial goals to avoid the costs of indecision.
Read more:
Insurance Can Be Used to Complement a Trust Strategy | Citywealth News
Digital Assets and PPLI Explained | Citywealth News
Private Placement Life Insurance | Citywealth News

Wimbledon Screen Returns to St Katharine Docks Bigger, Better, and Ready to Ace Wimbledon 2026
St. Katharine Docks returns with an upgraded outdoor screen for the Championships – now on Marble Quay with room for everyone!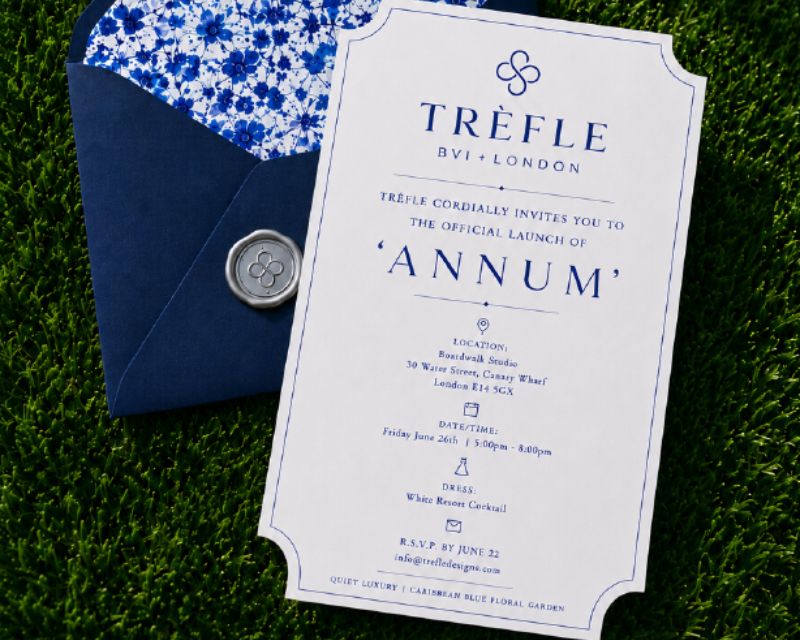
Invitation: Caribbean-British lifestyle brand pop up Canary Wharf
You are cordially invited to celebrate the London debut of ANNUM by TRÈFLE, our Caribbean-British lifestyle brand, as we unveil the first chapter of our exclusive capsule collection in a unique exhibition-style showcase.