The conflict clients can now see
Commission-led advice survived for decades because clients couldn’t see how it worked. That’s changing quickly, and clients are now asking a question some firms will find hard to answer.
A few years ago, an executive leader or business owner might ask about performance, or what we’d do differently with their portfolio. Now they arrive having run their existing arrangements through an AI assistant, often more than once, and they ask something much sharper: who else gets paid when I follow your advice?
That question used to take years of disappointment to reach. Now it takes an evening. For an industry that has relied on complexity to keep its economics out of view, that’s a significant shift, and I don’t think many firms have fully absorbed what it means.
Suitable was always a low bar
Much of the international advice market still works to a suitability standard. A recommendation has to fit the client’s profile. It doesn’t have to be the best option available to them, only a defensible one.
A fiduciary standard asks for more: act solely in the client’s best interest, recommend the best available option for the right reasons, and be open about who gets paid and how. Most people in the traditional industry understand the distinction. Fewer are honest about how much of the market sits on the wrong side of it.
In the Gulf, the expatriate advice market grew on commission-based products. Long terms, heavy early surrender penalties, and a large share of the commission paid upfront. Many of the people who sold them believed in what they were selling. The products were usually suitable. Whether they were the best option for a 40-year-old professional who might move to another country twice in the next decade is a different question, and clients are now asking it in hindsight.
Conflicts are wider than commission
It would be comfortable to treat this as a problem for the retail end of the market. It isn’t.
Conflicts show up in more sophisticated forms higher up the wealth scale. In-house funds on the recommended list. Platform rebates and retrocessions. Structures recommended partly because the firm can administer them and earn from them for years.
None of these are automatically wrong. The test is whether the structure was chosen because the family’s circumstances called for it, or because the firm’s revenue model did. From the outside, those recommendations can look identical. The client usually can’t tell the difference, and until recently had no easy way to find out.
The industry tends to argue about this through labels: commission, fee-based, fee-only. The labels matter less than two questions underneath them. Is every payment the firm receives disclosed to the client, clearly, and is the firm held to a fiduciary standard that obliges it to put the client’s interest first, whatever those payments are? A firm that can answer yes to both has made its conflicts visible and accountable. A firm that can’t is asking the client to trust something they have no way of checking.
When it costs something
Fiduciary duty is easy to uphold when the right answer and the profitable answer happen to match. It’s tested when they don’t, and that’s as true for firms as it is for individual advisers.
For a firm, committing fully to a fiduciary model means being willing to leave revenue on the table. It means disclosing every payment, including the ones clients might question, and dropping any arrangement that can’t survive that disclosure. It means reviewing legacy books of business and having some uncomfortable conversations about products that were sold under a different standard. I won’t pretend that’s painless. Plenty of firms look at what it would cost and decide it can wait.
For an individual adviser or financial life manager, the test is unlikely to arrive labelled as a fee question. It shows up when the right advice makes the relationship smaller: suggesting a client clear their mortgage instead of adding to their portfolio or talking them out of reinvesting the proceeds of an exit before they’ve decided what the money is for. Each of those conversations can cost the adviser something, and each one is easier to avoid than to have.
But a duty that only applies when it’s convenient isn’t a duty. Clients remember who gave them the answer that wasn’t in the adviser’s interest, and those are the relationships that last decades.
Why this matters more now
Other markets have already moved on this. The UK banned commission on investment advice at the end of 2012 under the Retail Distribution Review and required advisers to agree their charges openly with clients. Australia made similar reforms around the same time. Internationally mobile families increasingly bring those expectations with them. A family with a UK pension, a US-educated daughter and a business in the Gulf has seen transparent advice somewhere along the way, and they notice when they’re offered something murkier.
Then there’s the generational shift. The wealth that’s changing hands over the next decade is moving to people who expect to see how everything works, and who have the tools to check. They’re far less willing than their parents were to make an arrangement on trust.
And AI has changed what advice is actually for. When technical knowledge is free and instant, the adviser’s value sits in judgement, behavioural guidance and coaching, coordination across borders, and accountability for the outcome. Those are only worth paying for if the client can see exactly how the adviser is paid and knows the adviser is bound to put them first. Loyalty and accountability has become the product. Clients can now test for it.
Where the portfolio belongs
At AES we practise Financial Life Management, which works in a fixed order: purpose, then plan, then portfolio. That order only holds when the plan decides what gets recommended, and the firm’s revenue follows the plan rather than shaping it. A firm whose income depends on placing products needs the portfolio to come early, because that’s where the money sits. A fiduciary, with every payment disclosed and a duty to the client that overrides all of them, can leave the portfolio until last, where it belongs.
The industry spent a long time arguing about whether clients cared how their advisers were paid. They do, and now they can see it. The firms that will keep the next generation of international wealth are the ones that have nothing to hide when the question comes up.
About the author
Georgina Osborne-Stuart APFS is a Director of Financial Life Management at AES International in Dubai. AES is the only certified investment fiduciary in AMEA, advising internationally mobile professionals and families across the GCC.
She has spent 13 years in financial planning, advising senior partners at some of the world’s most respected law and accountancy firms. She combines deep technical expertise with a deeply personal approach, recognising that no two situations are alike and that great advice begins with truly listening.
For more information contact Georgina Osborne-Stuart, AES International – a Citywealth member.
Key Takeaways
- Clients now ask sharper questions about who else gets paid when following advice, changing the industry landscape.
- Many firms still operate on a suitability standard rather than a fiduciary standard, which prioritises the client’s best interest.
- Payment transparency is crucial; clients need to know how advisers are compensated to build trust and accountability.
- The rise of AI has transformed the value of advice, focusing on judgment and accountability instead of just technical knowledge.
- Firms that can openly disclose payments and uphold a fiduciary duty will retain the next generation of clients.
Subscribe to the Citywealth Weekly Newsletter to learn more about Private Wealth Management.
Read more:
Insurance Can Be Used to Complement a Trust Strategy | Citywealth News
Digital Assets and PPLI Explained | Citywealth News
Private Placement Life Insurance | Citywealth News

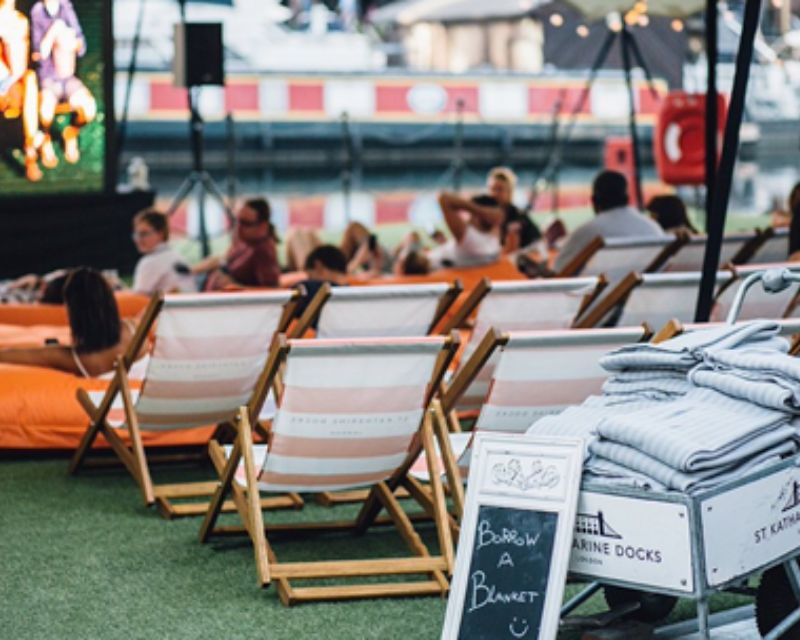
Wimbledon Screen Returns to St Katharine Docks Bigger, Better, and Ready to Ace Wimbledon 2026
St. Katharine Docks returns with an upgraded outdoor screen for the Championships – now on Marble Quay with room for everyone!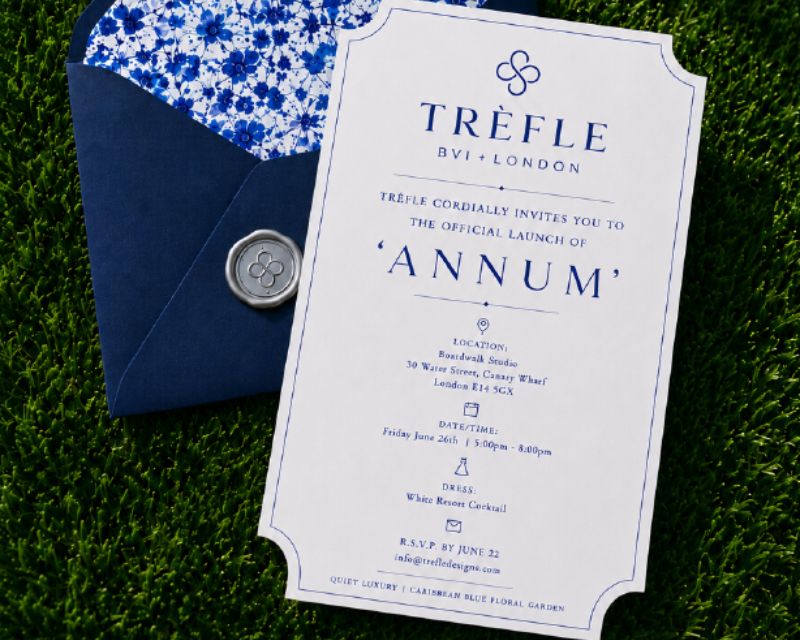
Invitation: Caribbean-British lifestyle brand pop up Canary Wharf
You are cordially invited to celebrate the London debut of ANNUM by TRÈFLE, our Caribbean-British lifestyle brand, as we unveil the first chapter of our exclusive capsule collection in a unique exhibition-style showcase.