


Tax Planning in Preparation for an Exit from the Business
Written by: Katherine Forster, Partner, Broadfield law firm who has 20 years experience in private wealth including in international tax structuring, offshore trusts and associated restructuring. “We advise founders on the transfer of trading company shares by way of share-for-share exchange into a family investment company (“FIC”), followed by a later sale of the trading company shares. This allows for the tax-free sale of the trading company shares due to the substantial shareholding exemption for corporation tax, with the proceeds of sale invested within a FIC. Establishing a FIC: The founder sets up a FIC, structured such that the founder retains control but economic value mostly lies with the next generation. To find out more, please click here.“
Share-for-share exchange: The founder then transfers his shares in the trading company to the FIC, in exchinvestment company (“FIC”), followed by a later sale of the trading company shares. This allows for the tax-free sale of the trading company shares due to the substantial shareholding exemption for corporation tax, with the proceeds of sale invested within a FIC.
The FIC later sells the shares in the trading company to a third-party buyer: If the conditions of the substantial shareholdings exemption (SSE) under Schedule 7AC TCGA 1992 are met, the gain is wholly exempt from corporation tax. The FIC must hold the trading company shares for at least 12 continuous months prior to the share sale; where section 135 TCGA treatment applies, the period pre share-for-share can be taken into account within the 12-month period. So, if the founder holds the original company’s shares for 6 months, exchanges them under section 135 TCGA, and then holds the acquiring company’s shares for another 6 months, the total aggregated holding period reaches the 12-month statutory threshold required for the SSE to apply.
The company whose shares are sold must be a trading company or holding company of a trading group throughout the period. Significant cash holdings can prevent the availability of the relief. The exemption applies automatically without a formal claim.
There is an anti-avoidance rule designed to deny the SSE if a main purpose of the arrangement is to secure a tax advantage rather than to conduct genuine commercial activity.
Since April 2017, there is no longer a requirement that the investing company is a trading company or a member of a trading group. This means that family investment companies (which are not trading companies) can now access the SSE, which they were unable to before April 2017.
Finance Act 2026 Changes
The rules on share-for-share exchanges have recently been tightened. Before 26 November 2025, a share-for-share exchange qualified for tax-neutral treatment provided there were bona fide commercial reasons and the arrangements were not designed mainly to avoid CGT or corporation tax. The Finance Act 2026 has however rewritten the test. HMRC can now deny relief where the main purpose, or even one of the main purposes of the arrangements is to reduce or avoid a capital gains liability.
This is a direct response to the Court of Appeal’s decision in Delinian Ltd v HMRC [2023] EWCA Civ 1281 (the “Euromoney” case), and it brings the legislation into line with HMRC’s long-held view of how these provisions should bite.
Importantly, HMRC accepts that deferral alone does not count as a tax advantage for these purposes — after all, deferral is precisely what section 135 TCGA is designed to achieve. The target is arrangements that reduce or eliminate a charge altogether, rather than simply pushing it down the road.
Where the test is failed, HMRC can now make just and reasonable adjustments to counteract the tax advantage. In practice, this gives HMRC a flexible tool to unpick arrangements it considers abusive — so structuring needs to be watertight.
Any share-for-share exchange with a value-shifting, loss-creation, or base-cost uplift element should be reviewed carefully against the new rules. If you are planning a reorganisation or acquisition involving share exchanges, early tax advice is essential.
Conclusion
With careful structuring around the anti-avoidance rules, it remains possible to benefit from the interaction between the share for share exchange rules with the SEE so as to exit from the business tax-free.
For more information contact Katherine Forster ,Partner in the Private Wealth team with over 20 years of experience at Broadfield law firm – a Citywealth member.
Key Takeaways
- Founders can transfer trading company shares into a Family Investment Company (FIC) for tax-free sales using the substantial shareholding exemption.
- Establishing a FIC allows founders to retain control while benefiting the next generation financially.
- Recent changes in the Finance Act 2026 tighten rules around share-for-share exchanges and focus on avoiding tax advantages.
- HMRC can now deny relief if tax avoidance is a main purpose; careful structuring is essential to gain benefits.
- Family Investment Companies now qualify for substantial shareholding exemption post-April 2017, offering more options for succession planning.
Subscribe to the Citywealth Weekly Newsletter to learn more about Private Wealth Management.
Read more:
Insurance Can Be Used to Complement a Trust Strategy | Citywealth News
Digital Assets and PPLI Explained | Citywealth News
Private Placement Life Insurance | Citywealth News

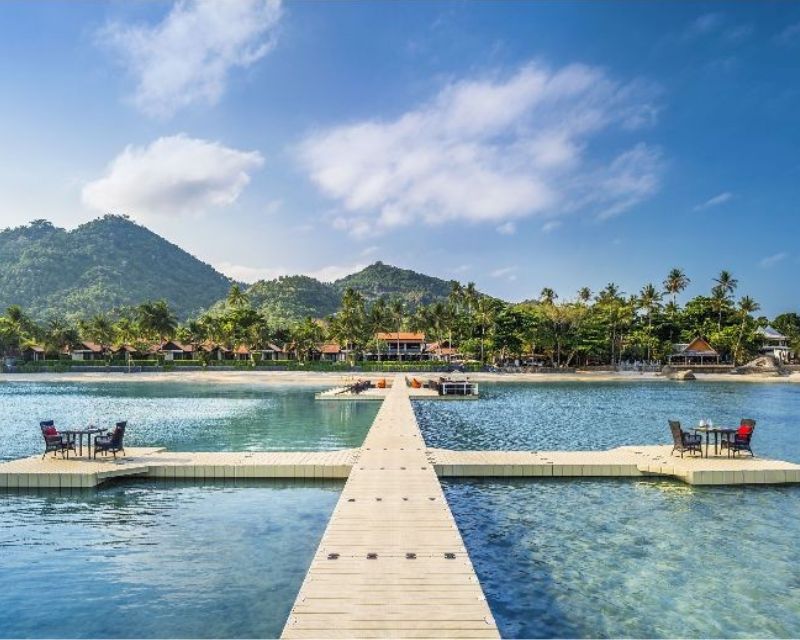
Fivelements unveils its next chapter as a global integrative wellbeing brand
Under GOCO Hospitality, the brand will debut its first new property in Koh Samui in 2027, with further expansion across Europe to follow.
An Evening with Leland Melvin
Retired NASA astronaut, engineer & NFL football player. Thursday, 10th September. Doors open at 5:30 p.m. Event begins at 6:15 p.m.