Cryptocurrency, digital assets and High-Net-Worth divorce
In 2009, Bitcoin was launched, opening wide the door for digital assets to become a mainstream financial trend. In the subsequent 17 years, a vast enterprise of cryptocurrency has entered our world, along with changing ways of managing our businesses, social enterprises and family life. With advancing technology, so much of our financial lives is now intangible, dramatically changing how, and how quickly, people can build wealth, and how much of this can be hidden. In the context of family law, specifically financial remedy proceedings on divorce, this can become an issue.
The role of cryptocurrency in financial portfolio
Cryptocurrency is also highly volatile. Markets shift rapidly due to supply and demand, making it a potentially risky asset to add to a financial portfolio.
Despite this, cryptocurrency is increasingly popular. Latest reports from HMRC in August 2026 showed that 240 people in the UK declared more than £1million in capital gains from crypto assets. HMRC’s annual Capital Gains Tax statistics published this data following the change made to the Self-Assessment form where there is now a unique section to identify income from cryptocurrency.
It is also, under the law, considered property, as confirmed by the High Court. It meets the four specific criteria set out in National Provincial Bank v Ainsworth {1965} 2 All ER 247:
- Have some degree of permanence.
- Definable;
- Identifiable by third parties;
- Capable in their nature of assumption by third parties; and
- Have some degree of permanence.
Digital assets in financial remedy proceedings
Marriage intertwines individual finances, whether the couple intends this or not. It is increasingly rare for couples to pool all their resources together. Rather, they will have some joint assets, such as the family home and a joint bank account, but most assets are kept in sole names. To some extent, this can protect individual assets in the event of divorce, particularly in cases of inheritance received by one party, or a property owned in a sole name from before the marriage. However, in lower asset divorces, these could still be subject to division depending on the needs of the parties. In HNW divorces, it could be more likely that the party in whose name the asset is held will retain it as “non-matrimonial”.
In divorce, all the assets are considered before determining individual ownership and whether any solely owned assets need to be divided. Cryptocurrency is not excluded from this, regardless of whose name it is held in, its international mobility or the difficulty in valuing the asset.
Cryptocurrency and full and frank financial disclosure
The first part of the process of dividing finances on divorce is understanding the landscape. Without this knowledge, negotiations cannot take place and there certainly cannot be a fair settlement reached.
In all financial remedies proceedings on divorce, parties individually complete a Form E, an extensive document examining all assets and liabilities in both sole and joint names, which is then exchanged. This document is particularly important for HNW clients who may have complex asset structures, extensive portfolios and, of course, digital assets.
However, digital assets can be difficult to disclose. There is not currently a specific section dedicated to them in the form, which can mean assets can easily be accidentally or purposefully excluded from the disclosure process. They can also be difficult to trace, potentially adding to the temptation to exclude them.
There can also be complications in valuing cryptocurrency, and it will usually need third-party professional insight to understand. Cryptocurrency is subject to fluctuations, dependent on various factors such as the demand for it, economic turbulence in the international market, and the status of different coins if a party invests in multiple currencies. As a result, its value can change drastically over the course of disclosure and financial negotiations. More administrative work is often required to ensure that disclosure is kept up to date, and the difficulties might necessitate a forensic accountant.
How are digital assets divided in divorce?
Cryptocurrency is subject to division and judicial orders in divorce in much the same way as any other asset due to its legal status as property. When financial disclosure is completed and professional valuations finalised, the negotiation process can begin. Importantly, anything held internationally also needs to be included in disclosure. The fluidity of cryptocurrency means it crosses borders very easily, but international assets are not excluded from division in divorce. Whether parties choose to do this through solicitor negotiation, mediation, or, as a last resort, a court application, potentially makes a difference to the outcome.
Should parties be able to come to an agreement between themselves, alongside specific legal advice, they have far more control of how assets are divided. For example, should the owner of cryptocurrency wish to keep their entire portfolio, they may be able to do so provided the other party has a matched share of another asset, depending on the valuation.
Where third parties are involved, particularly in a court application, control is passed to someone presented purely with the facts of the case, rather than someone who understands the nuances of the specific financial and family dynamic. In such cases, a judge will decide on how best to divide all the assets, including any digital assets. This will be based on the principle of fairness, which does not necessarily mean a 50/50 split. Equally, crypto held in one party’s sole name will not necessarily be automatically shared.
Important considerations for High-Net-Worth individuals
Protecting cryptocurrency in divorce
One of the best ways HNWs can ringfence any asset, including cryptocurrencies, is through a prenuptial or postnuptial agreement. Prenups are documents signed ahead of a marriage to set out financial ownership, and what should happen to particular assets in the event of a divorce. They can be used to protect inheritance, property in a sole name, pre-acquired wealth and much more. A postnuptial agreement does the same, but can be drawn up after the wedding. Neither can be created if the couple has already separated or there are questions about the relationship.
It’s also important to note that they are not presently entirely legally enforceable. Should a nuptial agreement not meet the specific criteria in its drafting, for example that there was no coercion involved in the signing of the document, or that it leaves one party unable to meet their needs, it will not be upheld by a court. However, provided the proper measures are taken, they can provide considerable weight in a dispute.
Capital Gains Tax
Another important factor is that cryptocurrency is subject to CGT because HMRC does not treat it as money, so it is not subject to income tax. In financial proceedings, this can have a significant impact – an increase in the value of an asset can trigger CGT, potentially reducing its value. It may be more suitable to offset the asset against another rather than share it in divorce.
Conclusion
As family lawyers, we are seeing an ever-growing number of cases involving cryptocurrency and other digital assets. These cases can be complicated, and financial proceedings can take considerably longer as external professionals need to be involved alongside expert legal advice. The best preparation HNW individuals can undertake is firstly to have a nuptial agreement in place, but also to keep clear records of what is owned, where it is held, and whether it can be liquidated.
For more information contact Shivi Rajput, Stove Family Law – a Citywealth member.
Key Takeaways
- Cryptocurrency digital assets are becoming increasingly integral in financial portfolios and can complicate divorce proceedings.
- HNW individuals must understand the valuation, disclosure, and division of cryptocurrency during divorce, as it is treated as property by law.
- Form E is crucial for disclosing assets, but digital assets can be tricky to include and value accurately.
- Prenuptial and postnuptial agreements can protect cryptocurrency in case of divorce, though they aren’t fully legally enforceable.
- Capital Gains Tax applies to cryptocurrency, impacting its value and division during divorce, making proper record-keeping essential.
Subscribe to the Citywealth Weekly Newsletter to learn more about Private Wealth Management.
Read more:
Insurance Can Be Used to Complement a Trust Strategy | Citywealth News
Digital Assets and PPLI Explained | Citywealth News
Private Placement Life Insurance | Citywealth News

Wimbledon Screen Returns to St Katharine Docks Bigger, Better, and Ready to Ace Wimbledon 2026
St. Katharine Docks returns with an upgraded outdoor screen for the Championships – now on Marble Quay with room for everyone!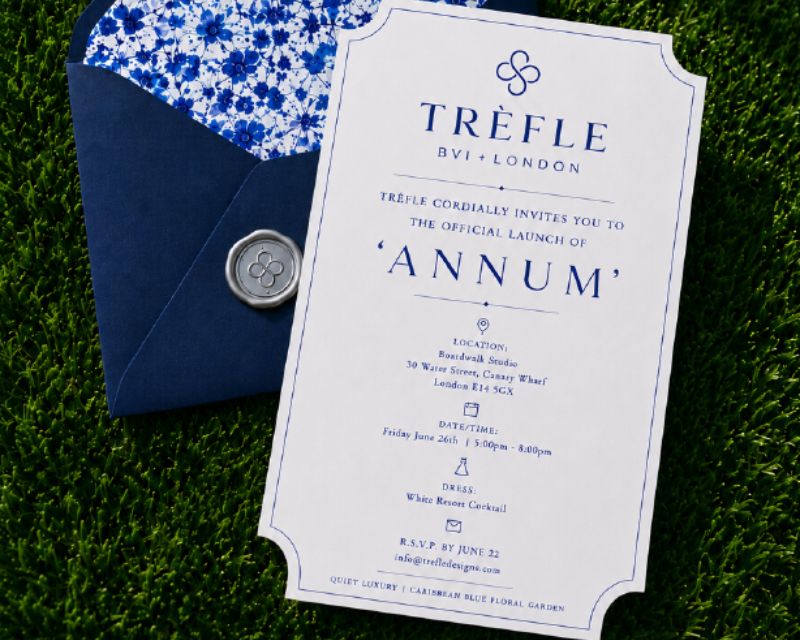
Invitation: Caribbean-British lifestyle brand pop up Canary Wharf
You are cordially invited to celebrate the London debut of ANNUM by TRÈFLE, our Caribbean-British lifestyle brand, as we unveil the first chapter of our exclusive capsule collection in a unique exhibition-style showcase.