Latest in the Middle East: CT Law Updates in the UAE
Fairway’s Chris Mourant, Associate Director, discusses recent ministerial decisions that have been published since the introduction of the Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses (the “UAE CT Law”).
Introduction of Corporate Tax in the UAE
The introduction of corporate tax in the UAE under Federal Decree-Law No. 47 of 2022 (the “UAE CT Law”), which came into effect on 1st June 2023, has driven significant efforts among businesses to understand and comply with the new tax regulations. The most recent key development in this area involves the treatment of unincorporated partnerships, foreign partnerships, and family foundations under the UAE CT Law.
Key Provisions Under Articles 16 and 17
Pursuant to Article 16 of the UAE CT Law, an unincorporated partnership would by default be treated as a look-through entity. Partners would be considered as conducting the business of the unincorporated partnership and would be liable to tax accordingly. The UAE CT Law also provides an option for the unincorporated partnership to make an application to the authorities to be taxed at the partnership level rather than the partner level.
Furthermore, Article 16 of the UAE CT Law also provided certain conditions under which a foreign partnership could be treated as an incorporated partnership. Similarly, Article 17 prescribed the conditions under which a UAE foundation could be treated as an unincorporated partnership.
New Tax Transparency Options for Family Foundations
In May 2023, Ministerial Decision No. 127 of 2023 was issued to clarify various aspects of the UAE CT Law and provided additional conditions to be satisfied by unincorporated partnerships, foreign partnerships and family foundations.
On 18th November this year, the UAE Ministry of Finance published Ministerial Decision No. 261 of 2024, superseding Ministerial Decision No. 127 of 2023, on unincorporated partnerships, foreign partnerships, and family foundations. This Decision is applicable retrospectively from 1st June 2023.
In effect, holding companies, foundations, and other juridical persons that are wholly owned and controlled by a family foundation can elect to be treated as tax transparent entities, provided that the following requirements are met:
- the juridical person is wholly owned and controlled by the family foundation either directly or indirectly through an uninterrupted chain of other entities which are treated as unincorporated partnerships in accordance with the UAE CT Law.
- The juridical person meets the conditions of clause 1 of Article 17 of the UAE CT Law.
This means that the company’s income may be attributed directly to the beneficiaries of the UAE foundation resulting in a significant tax advantage for a family foundation holding assets within the UAE.
Implications for Private Wealth and Succession Planning
The clarity provided by Ministerial Decision No. 261 of 2024 is expected to be well-received by private wealth advisors and experts. By aligning the tax treatment of family foundations with the UAE corporate tax framework, the decision enhances the appeal of establishing family foundations as part of succession planning strategies.
Strengthening the UAE’s Reputation
Fairway anticipates that the decision will provide the necessary clarity to advisors as to the tax treatment of such structures which will result in a number of discussions with families regarding their succession and wealth structuring needs.
The decision underscores the UAE’s commitment to fostering a favourable environment for family-owned structures, ensuring compliance while offering robust tax advantages.
For more information contact Chris Mourant, Fairway – a Citywealth member.
Key Takeaways
- The UAE introduced corporate tax under Federal Decree-Law No. 47 of 2022, effective from 1st June 2023, which affects unincorporated partnerships and family foundations.
- Article 16 treats unincorporated partnerships as look-through entities, while allowing an option for taxation at the partnership level.
- Ministerial Decision No. 261 of 2024 clarifies tax treatment for family foundations, making certain juridical persons tax transparent for tax advantages.
- The new provisions enhance the appeal of family foundations in private wealth and succession planning strategies.
- Fairway anticipates increased discussions among families regarding wealth structuring due to the clarity provided by the latest ministerial decision.
Subscribe to the Citywealth Weekly Newsletter to learn more about Private Wealth Management.
Read more:
Insurance Can Be Used to Complement a Trust Strategy | Citywealth News
Digital Assets and PPLI Explained | Citywealth News
Private Placement Life Insurance | Citywealth News

Wimbledon Screen Returns to St Katharine Docks Bigger, Better, and Ready to Ace Wimbledon 2026
St. Katharine Docks returns with an upgraded outdoor screen for the Championships – now on Marble Quay with room for everyone!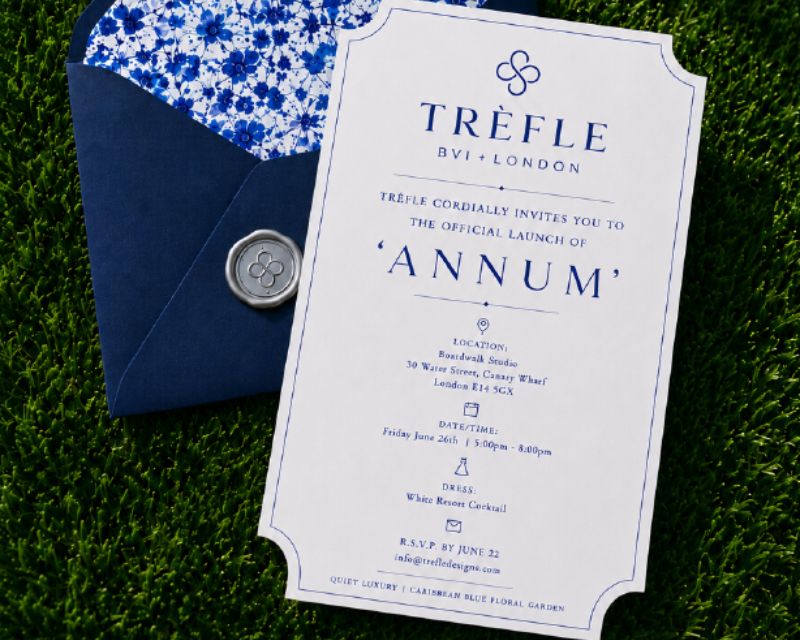
Invitation: Caribbean-British lifestyle brand pop up Canary Wharf
You are cordially invited to celebrate the London debut of ANNUM by TRÈFLE, our Caribbean-British lifestyle brand, as we unveil the first chapter of our exclusive capsule collection in a unique exhibition-style showcase.