Why Financial Life Management matters in the age of AI
Something has changed in the first meetings I hold with new clients, and it happened fast.
Two years ago, a senior executive or business owner would arrive with questions. Where should the pension sit if we move again? What does an exit mean for the family’s tax position? Increasingly, they arrive with answers. A product name, a structure, sometimes a full strategy, assembled over several evenings with an AI assistant.
I understand why. These tools are remarkable. They explain complex financial mechanisms clearly, at any depth, at any hour, for nothing. In twenty years of advising international families, I’ve never seen clients arrive so well informed, and I mean that as a genuine compliment to them and the technology.
But something important is getting lost in the translation from information to decision, and it’s worth talking about.
What AI has changed, and what it still can’t get right
For most of my career, part of an adviser’s value was simply knowing things the client didn’t. How an offshore bond is taxed. What domicile means for inheritance. How pension rules treat a leaver. Knowledge built over years of practice and countless exams is now available to anyone and everyone with a chat window, and honestly, good riddance. Advice that was only information deserved to lose its price tag.
What no chat window holds is context. An AI produces an answer from what it was told, and however long the conversation, it’s unlikely to know in depth about the half-formed plan to return to the UK in five years, the daughter who may study in America, the parent who may need care, or the business partner whose exit timeline shapes everything. These things rarely make it into a prompt, partly because they feel irrelevant at the time, and partly because people don’t yet know they matter.
In a financial life that crosses borders, those details, and more importantly how they make the client feel, are usually what truly matters. Every experienced adviser has watched a technically correct answer become an expensive mistake because it was acted upon without any real scrutiny from a human.
The order of decisions is the discipline
AES practices a discipline called Financial Life Management, and its core is an order ofoperations: purpose, then plan, then portfolio.
Notice where AI-assisted research typically enters this sequence: at the end, with a portfolio-level answer, before purpose or plan exist. The order has been reversed. In that sense, nothing here is new. The traditional financial industry has always led with products, because commissions rewarded whatever could be sold first. And a product is only ever the tip of the iceberg. The visible holding sits above a far larger mass of tax positions, family circumstances, timings and intentions, and it’s the part below the waterline that does the damage. An AI recommendation, arriving polished and product-first, recreates that old sales model at greater speed and scale.
When the product comes first, a well-documented bias called ‘anchoring’ takes over. It’s a thoroughly human response, and it catches the most capable people. Tversky and Kahneman showed in 1974 that the first option a person encounters pulls every later judgement towards it. The research question shifts from “what does my life need” to “should I buy this thing”, and the shift goes unnoticed because anchoring never announces itself.
There’s a commercial layer to this as well. Providers now optimise their content to be the answer AI assistants give, just as they once optimised for search engines. The trade press has begun documenting how quickly AI is reshaping financial services marketing. When a chat window names a product, it’s reflecting who competed hardest for visibility. Suitability for any individual life was never part of the calculation.
Advice carries something an answer can’t
There’s one more difference between an answer and advice, and to my mind it’s the decisive one: responsibility.
When a fiduciary adviser makes a recommendation, someone is accountable for it. They’ve understood the whole picture, they’re paid by the client rather than by a provider, and they carry a duty to that client’s interests over years and decades. An AI assistant carries no duty to anyone. If you act on its answer without any adviser involved and it turns out to be wrong for your life, the consequences are entirely yours, and they tend to surface a decade later, when they’re hardest to fix. This is also why a good adviser won’t simply execute a product a client brings to a first meeting. Any recommendation, and the responsibility that comes with it, has to be the adviser’s own, which means the questions have to come first.
This is why I’d caution strongly against treating AI research as a route to running your own financial life across borders. The technology makes self-direction feel safer at exactly the moment complexity makes it more dangerous. Cross-border tax, succession and pension decisions interact in ways that punish confident generalisations, and the cost of an unasked question compounds silently for years.
What good advice looks like now
None of this is an argument against the technology. Some of the best first meetings I’ve had this year were with people who’d used AI thoroughly and brought the transcript in with them. Their questions were sharper. The conversations went deeper, and we got there faster. That’s the model worth recommending: use AI to come in better informed, then let a proper advice conversation do the thing AI can’t, work out what you actually need, and take responsibility for getting it right.
It’s worth being honest about what this technology has ended. Information was never the hard part, and now it’s free and instant, that’s clearer than ever. Anyone can get a decent answer to a single question. What AI can’t do is see your whole situation, weigh the trade-offs, coordinate every part of your financial life, read what’s behind your answers, the hesitation, the body language, how you actually feel about it all, and stand behind the outcome. That was always the real work, and it still needs a human.
Because in the end, financial success is determined less by what people know than by what they do, and keep doing. The most expensive mistakes I see are invisible ones: the returns never earned while a good decision sat waiting on just a little more research. Helping clients cross the gap between knowing and doing, at the right moment and for their own reasons, is where a financial life manager truly earns their place.
AI has stripped out everything that was only pretending to be advice, and made the real thing easier to spot. Real advice starts with your life and what your money is for. A plan holds it together. And it treats the portfolio as the last decision, not the first. That order- purpose, then plan, then portfolio – is the rarest and most valuable thing in finance, and it’s the whole basis of financial life management. It’s also the part you can’t do alone, however good the technology gets.
About the author
Georgina Osborne-Stuart APFS is a Director of Financial Life Management at AES International in Dubai. AES is the only certified investment fiduciary in AMEA, advising internationally mobile professionals and families across the GCC.
She has spent 13 years in financial planning, advising senior partners at some of the world’s most respected law and accountancy firms. She combines deep technical expertise with a deeply personal approach, recognising that no two situations are alike and that great advice begins with truly listening.
View Georgina’s Leaders List profile here Georgina Osborne-Stuart, AES International.
Subscribe to the Citywealth Weekly Newsletter to learn more about Private Wealth Management.
Read more:
Insurance Can Be Used to Complement a Trust Strategy | Citywealth News
Digital Assets and PPLI Explained | Citywealth News
Private Placement Life Insurance | Citywealth News

Wimbledon Screen Returns to St Katharine Docks Bigger, Better, and Ready to Ace Wimbledon 2026
St. Katharine Docks returns with an upgraded outdoor screen for the Championships – now on Marble Quay with room for everyone!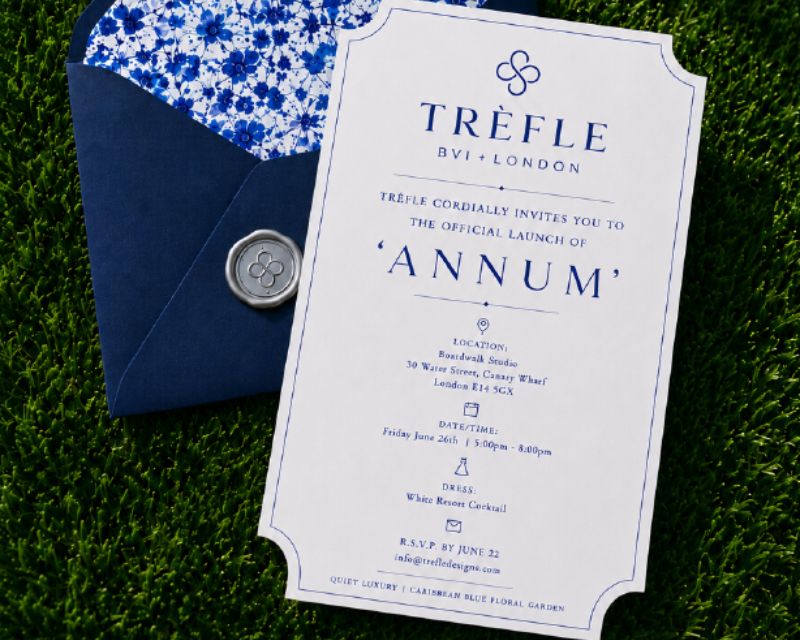
Invitation: Caribbean-British lifestyle brand pop up Canary Wharf
You are cordially invited to celebrate the London debut of ANNUM by TRÈFLE, our Caribbean-British lifestyle brand, as we unveil the first chapter of our exclusive capsule collection in a unique exhibition-style showcase.